
How do I buy a home for the first time in St. Johns?
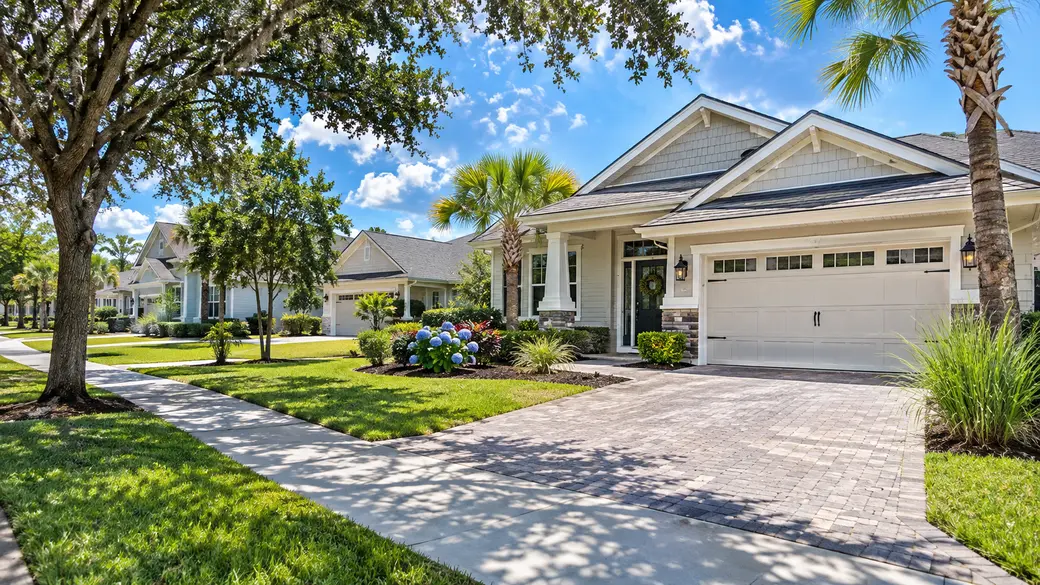
Short Answer
To buy your first home in Saint Johns, FL, start with mortgage preapproval, set a total monthly ownership budget, and compare homes by location, condition, and community costs. Make an offer with appropriate inspection and financing terms, complete lender and property due diligence, then close after final approval.
In order, the steps are:
- Get preapproved and set a total monthly budget.
- Check first-time buyer programs and complete any required homebuyer class.
- Compare St. Johns communities by price, fees, school zone, and commute.
- Tour homes, in person or by live video.
- Make an offer with inspection and financing protections.
- Complete inspections, appraisal, and lender and title review.
- Close, record the deed, and receive the keys.
More Info
A preapproval helps establish a purchase range before touring homes, but the mortgage payment is only one part of the budget. For a Saint Johns home, review property taxes, homeowners insurance, homeowners association fees, and any community development district fees where applicable. Ask for these costs early, including whether fees can change and what they cover. For resale homes, use the inspection period to evaluate major systems, permits, and repair needs. For new construction, compare the builder's contract, included features, completion timing, warranties, and any costs for upgrades. Confirm the property's assigned school attendance zone directly with the school district before relying on it in a purchase decision.
What a First Home Costs in St. Johns: 2026 Benchmarks
St. Johns is an unincorporated area of St. Johns County, ZIP code 32259, that includes Fruit Cove, Switzerland, and Julington Creek, along with communities such as RiverTown and Durbin Crossing. These dated figures give a starting point:
- Median sold price: Over the 12 months ending in mid-October 2026, 2,156 homes closed in ZIP 32259 at a median of $505,000, down 1.0% from a year earlier, with a median of 43 days on market (realMLS).
- Community medians: $510,000 in Julington Creek Plantation (12 months ending October 14, 2026), $470,000 in Durbin Crossing (12 months ending October 1, 2026), and $548,250 in RiverTown (as of November 13, 2026).
- New-construction entry points: Builder starting prices in RiverTown's Meadows neighborhood were about $259,990 for attached homes of roughly 1,200 square feet and about $335,000 to $347,000 in Glades at Meadows, though builder prices change often.
- Mortgage rate: The average 30-year fixed mortgage rate was 7.11% as of November 12, 2026 (Freddie Mac).
At the $505,000 ZIP median and a 7.11% rate, estimated principal and interest is about $3,227 per month with 5% down ($25,250 down payment) and about $2,718 per month with 20% down ($101,000). Those figures exclude taxes, insurance, HOA and CDD charges, and mortgage insurance, which usually applies when the down payment is under 20%.
Taxes, Insurance, HOA, and CDD Fees to Add
- Property taxes: St. Johns is unincorporated, and the 2025 total millage for unincorporated St. Johns County was about 13.47 mills. A new owner's bill is based on the new assessed value, not the seller's old bill.
- Homestead exemption: A permanent primary residence may qualify for a 2026 exemption of up to $51,411 (St. Johns County Property Appraiser). Florida voters approved Amendment 3 on November 3, 2026, which raises the non-school exemption beginning in 2027, but people who are not Florida residents as of December 31, 2026 receive a smaller initial exemption until the fifth year of exemption, so relocating first-time buyers should plan around that rule.
- Homeowners insurance: The average St. Johns County premium including wind coverage was $2,883 as of March 31, 2026, or about $240 per month (Florida Office of Insurance Regulation). Your quote depends on roof age, construction, and wind-mitigation features.
- CDD assessments: These appear on the property tax bill and vary widely. Julington Creek Plantation's was $1,385.44 for single-family homes in FY2025, Durbin Crossing's ranged from roughly $2,245 to more than $4,050 by lot width in the FY 2025-26 schedule, and RiverTown's ran roughly $2,000 to $2,660. Bartram Ranch and SilverLeaf have no CDD, and SilverLeaf's amenities are funded through HOA dues (about $1,200 per year for the master association, before neighborhood dues).
- HOA dues: These vary by community and may cover amenities, landscaping, and management.
A mortgage calculator can help you test different prices and down payments before you talk with a lender.
Inspections and Due Diligence
Inspection steps differ between resale and new construction. For a resale home, the widely used Florida purchase contract typically sets a 15-day inspection period unless the parties agree otherwise, and buyers commonly add a wind-mitigation inspection, a four-point inspection (roof, electrical, plumbing, and HVAC) when insurers ask for it, and a sewer scope or pool inspection where relevant. For new construction, plan a pre-closing walkthrough, review the punch list, and understand the builder's warranty process. In both cases, check the parcel's flood zone, which matters most near the St. Johns River and its creeks, and request HOA and CDD documents during the inspection period.
Check the School Zone by Address
The St. Johns County School District ranked first among Florida's 67 districts for the 2025-26 school year with 910 accountability points. Zones are address-specific and can change as new schools open, and communities in St. Johns generally feed schools such as Creekside High School or Bartram Trail High School depending on the parcel. Use the district's attendance zone locator before you make an offer, and see our guide to St. Johns County schools for how to verify a zone.
How do I buy a home for the first time in St. Johns?
A first-time buyer commonly has not owned a principal residence during the three years before purchase. Saint Johns is an unincorporated area of St. Johns County, so county programs may be relevant. The County's SHIP Down Payment Assistance program requires applicants to complete its HUD-certified homebuyer education class and obtain a certificate within the prior year. It also has income, credit, occupancy, lender-preapproval, and live-or-work-in-the-county conditions. St. Johns County's program requirements should be reviewed before structuring an offer. Florida Housing programs may also be available through participating lenders, including assistance tied to eligible first mortgages; program rules and available funds can change.
St. Johns County SHIP Down Payment Assistance: Key Requirements
According to the county's program page, updated in July 2026, the SHIP program includes these conditions:
- Award: Up to $100,000, as a 0% interest, 15-year deferred second mortgage that is forgiven at 10% per year beginning in year six, with no forgiveness in years one through five.
- Income: Households up to 120% of area median income, using the Florida Housing income limits effective May 1, 2026.
- Residency: You must currently live or work in St. Johns County for at least 12 consecutive months, and the home must be your primary residence with a homestead filed.
- First-time buyer: You must not have owned a home in the last three years.
- Credit and class: A credit score of 640 or higher, and a Homebuyer Education class certificate from the county's HUD-certified counselor, which is good for one year.
- Price and loan: The purchase price cannot exceed 70% of the current SHIP purchase price limit, and you must be approved for a fixed-rate first mortgage by a participating lender.
- Funding: Funding is subject to availability, and the county maintains a waitlist when eligible applicants exceed funds. Repayment is due in full on sale, title transfer, or loss of the homestead exemption.
To get started, contact the county's Housing and Community Development office at (904) 827-6890.
Other First-Time Buyer Help
Florida Housing's Hometown Heroes program offers eligible essential workers 5% of the first mortgage (a minimum of $10,000 and a maximum of $35,000) as a 0% interest deferred second mortgage that is not forgivable, and it cannot be combined with other Florida Housing down payment assistance. Funding is limited and available on a first-come basis, so ask a participating lender about current availability. Standard loan options also include conventional loans, which allow as little as 3% down, and FHA and VA loans. Credit-score minimums vary by program and lender, and the baseline conforming loan limit for a one-unit home in St. Johns County is $832,750 in 2026, so most first-time purchases in St. Johns fall well below the jumbo threshold.
Our guide for first-time home buyers in St. Johns County covers more of the financing detail.
Related Questions
What should I ask about HOA and CDD fees before buying in Saint Johns?
Request the current fee schedule, governing documents, budget, reserve information, and any pending assessments. Include recurring community charges in the lender's monthly-cost review.
Also ask which part of the CDD assessment is debt service and which is operations and maintenance, when the bonds end, and whether the amount is tied to lot width. In St. Johns, CDD assessments range from none in Bartram Ranch and SilverLeaf to more than $4,050 in parts of Durbin Crossing.
Can I buy a Saint Johns home remotely?
Yes, a remote purchase can include live video showings, inspections, document review, and final walkthrough coordination. Buyers should still review disclosures, inspection findings, and contract deadlines carefully.
Florida permits remote online notarization under Chapter 117, Part II of the Florida Statutes, and the deed is recorded in the Official Records of the St. Johns County Clerk of Court. Some addresses in ZIP 32259 carry a "Jacksonville" mailing label while sitting in St. Johns County, so confirm the county, school zone, and tax district for any address you consider.
How do I compare new construction with a resale home?
Compare the complete cost, including upgrades, closing terms, timing, insurance, fees, condition, and repair obligations. A resale home may offer established features, while a new home may involve builder-specific contract terms and construction milestones.
In St. Johns, about 25% of single-family closings in St. Johns County in August 2026 were newly built homes, so both paths are widely available. Our new construction page shows current builder options.
What credit score do I need to buy a first home in St. Johns?
It depends on the loan program. The county's SHIP program and Hometown Heroes both require a score of at least 640, conventional loans commonly start at 620, and FHA loans can allow lower scores with a higher down payment. Individual lenders may set higher minimums, so ask your lender which program fits your profile.
How long does it take to buy a first home in St. Johns?
Most purchases take about 30 to 60 days from accepted offer to closing when financing is already in motion, and many first-time buyers spend one to three months searching beforehand. County down payment assistance adds steps, including the homebuyer class and lender approval, so start those early.
Which St. Johns communities should a first-time buyer compare?
Compare communities by total monthly cost, not only price. Durbin Crossing's $470,000 median sits below the ZIP median of $505,000, Julington Creek Plantation's $510,000 sits just above it, RiverTown has newer homes and a $548,250 median with a mid-range CDD, and SilverLeaf and Bartram Ranch avoid a CDD. Your commute matters too: measured weekday-morning drives from Julington Creek were about 38 minutes to Downtown Jacksonville and 29 minutes to the St. Johns Town Center.
Tips from Move Me to Florida Team
- Round Table Realty can help buyers compare Saint Johns communities by school-zone considerations, commute patterns, amenities, new construction options, and resale-home tradeoffs. The goal is to identify practical differences that affect the purchase decision.
- For buyers purchasing from outside Northeast Florida, Josh Cotton can preview homes, conduct detailed live video walkthroughs, coordinate inspections and repairs, and communicate with builders and listing agents.
- To discuss a first purchase in Saint Johns, contact Josh Cotton at Round Table Realty at 904-982-8461. He can help organize property comparisons and transaction steps without assuming that one neighborhood or home type fits every buyer.
- The Move Me to Florida Team works with first-time buyers and luxury buyers alike. Josh has seven years of real estate experience and has personally participated in more than 320 transactions with over $200 million in closed sales associated with those transactions, so the guidance comes from a wide range of St. Johns County purchases.
- You can also email josh@welcomehome904.com or use the contact page, and the relocation page explains how remote buying works from the first call.
Updated November 2026. Rates, program rules, and available funds change, so confirm current details with your lender and the program administrator before you make an offer.
Categories
Recent Posts

I'm Josh Cotton, a Northeast Florida Realtor with the Move Me to Florida Team at Round Table Realty. I specialize in helping buyers, sellers, and relocating clients navigate St. Johns County, Nocatee, Ponte Vedra Beach, St. Augustine, and Jacksonville, with expertise in residential sales, new construction, and luxury real estate.
With over 7 years of experience, 320 transactions and over $200 million in closed sales, I bring a wealth of experience, firsthand local knowledge, strategic insight, and personalized guidance to every real estate journey.